Germany requires every resident to carry health insurance. That is not a suggestion or a cultural norm — it is a legal obligation under the German Social Code (SGB V). When you move to Germany from the US, you must enroll in either the statutory system (GKV, Gesetzliche Krankenversicherung) or, if you qualify, private health insurance (PKV, Private Krankenversicherung). Your first practical step: determine which system you are eligible for before you arrive, and secure visa-compliant proof of coverage before your appointment at the immigration office.
Here is how the two systems divide most newcomers:
- GKV (statutory): Employees earning below the annual mandatory insurance threshold, students, pensioners, and most people in marginal employment are automatically required to join a statutory fund.
- PKV (private): Employees whose gross income exceeds the annual threshold, the self-employed, freelancers, and civil servants (Beamte) can opt for private coverage.
- Immediate next step for US readers: Check your employment status and income level against the current threshold. If you are eligible for PKV, compare tariffs before signing anything. If you fall into GKV, contact a statutory fund directly or use an English-language broker to register. Either way, US domestic health plans do not meet German legal requirements for residents, so do not assume your existing coverage transfers.
Around 90 percent of people in Germany are members of a statutory fund. That figure alone tells you where most expats land — but the 10 percent in private insurance includes a disproportionate share of high earners and self-employed professionals, which is exactly the profile of many Americans relocating for work.
Key Takeaways
Germany's dual health insurance system requires every resident to carry cover, and your income, employment status, and family situation determine which system you legally belong to.
| Point | Details |
|---|---|
| Coverage is compulsory | Every resident must hold GKV or PKV; gaps in coverage carry legal and financial consequences. |
| PKV eligibility is income-driven | Employees above the annual mandatory insurance threshold, the self-employed, and civil servants can choose private cover. |
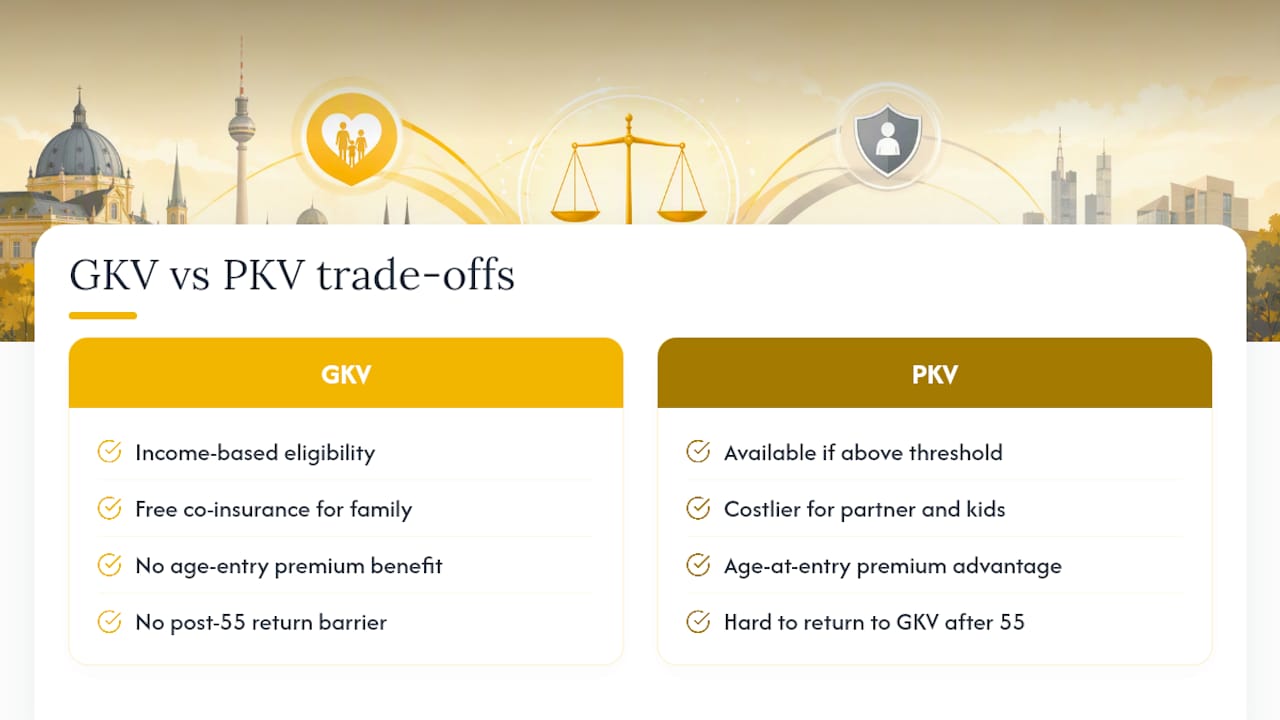
| Family co-insurance changes the math | GKV co-insures non-earning spouses and children free; PKV requires a separate premium for each family member. |
| Switching after 55 is severely restricted | Returning to GKV from PKV is difficult after age 55, making the initial choice a long-term financial decision. |
| Myhealthcarebroker | Offers a free eligibility check and English-language PKV comparison to help expats choose and apply correctly. |
Table of Contents
- 1. How Germany's health insurance system actually works
- 2. Who must join GKV and who can choose PKV
- 3. How much German health insurance costs
- 4. What GKV covers versus what PKV can offer
- 5. How to enroll in German health insurance step by step
- 6. How to decide between GKV and PKV
- 7. Switching between GKV and PKV: rules and real risks
- 8. Using U.S. health insurance in Germany: what actually works
- 9. Practical arrival checklist for U.S. residents moving to Germany
- 10. When a specialist broker makes the difference
- Myhealthcarebroker helps you get it right from the start
- An honest perspective on the GKV vs. PKV decision
- Sources
1. How Germany's health insurance system actually works
Germany runs a dual system, and the two tracks operate on fundamentally different financial logic.
The statutory system (GKV)
GKV is built on the solidarity principle: your contribution is calculated as a percentage of your income, not your health risk. A 28-year-old in perfect health and a 55-year-old with a chronic condition pay proportionally to what they earn, and both receive the same standardized package of benefits. The legal framework is the German Social Code Book V (SGB V), which defines the mandatory benefit catalog (Pflichtleistungen) that every statutory fund must cover.
The general contribution rate is a percentage of gross income, split equally between employer and employee. On top of that, each fund charges an additional surcharge called the Zusatzbeitrag, which varies by fund and changes annually. Comparing funds on their Zusatzbeitrag, not just the base rate, can meaningfully affect your monthly cost.
The private system (PKV)
PKV works on individual risk pricing. Insurers assess your age, health status, and chosen coverage level when you apply, then set a premium accordingly. You pay that insurer directly, and the insurer reimburses you after you submit receipts — rather than billing the fund directly as in GKV. This reimbursement model gives you more flexibility with providers but requires you to manage paperwork and sometimes carry costs upfront.
| Feature | GKV (statutory) | PKV (private) |
|---|---|---|
| Premium basis | Percentage of gross income | Age and health risk at entry |
| Employer contribution | 50% of total contribution | Up to a defined statutory maximum |
| Family coverage | Children and non-earning spouses co-insured free | Separate premium for each family member |
| Benefit standard | Uniform catalog set by SGB V | Tariff-dependent, often broader |
| Billing model | Fund billed directly by provider | You pay, then claim reimbursement |
| Specialist access | Referral often required | Direct access, shorter wait times typical |
Statutory and private insurance differ most sharply on family coverage and billing flow — two factors that matter enormously once you factor in a partner or children.
2. Who must join GKV and who can choose PKV
Your legal category determines your options. This is not a free choice for most people.
Compulsory GKV membership applies to:
- Employees with gross annual income below the mandatory insurance threshold (Versicherungspflichtgrenze), which is adjusted annually.
- Students enrolled at a German university (up to age 30, or within 14 semesters).
- Pensioners receiving a German statutory pension who have been GKV members for a qualifying period.
- Workers in marginal employment (Minijobs) below the earnings threshold.
- People receiving unemployment benefits (Arbeitslosengeld).
Who may opt for PKV:
- Employees whose gross annual income exceeds the mandatory insurance threshold for at least one year.
- Self-employed and freelancers (Selbstständige/Freiberufler) — they are never subject to compulsory GKV and can choose either system from day one.
- Civil servants (Beamte) — the state covers part of their healthcare costs through a subsidy (Beihilfe), making PKV the standard choice.
PKV eligibility is commonly available to high earners, the self-employed, and civil servants, and the Basistarif provides a legal safety net for those who can no longer afford standard private tariffs.
The table below shows where common expat scenarios typically land:
| Expat scenario | Typical system | Notes |
|---|---|---|
| Employee, income below threshold | GKV (compulsory) | No choice; must enroll in a statutory fund |
| Employee, income above threshold | PKV (optional) | Can stay in GKV voluntarily or switch to PKV |
| Freelancer / self-employed | PKV or voluntary GKV | No compulsory GKV; PKV often more cost-effective |
| Student at German university | GKV (student tariff) | Special low-rate student contribution applies |
| Civil servant (Beamter) | PKV (standard) | State Beihilfe subsidy makes PKV the norm |
| Cross-border worker (EU) | GKV or home-country cover | Depends on employment location and EU coordination rules |
Migrant- and student-specific enrollment rules differ from standard employee procedures, so check your specific category before assuming the standard employee path applies to you.
3. How much German health insurance costs
Cost is where the two systems diverge most sharply for high earners, and where the math can surprise you.
GKV contribution mechanics
The general rate is split 50/50 between employer and employee, so you personally pay half of the gross income percentage. Add your fund's Zusatzbeitrag (the fund-specific surcharge), split equally again; your total personal share depends on the fund you choose. Contributions are calculated only up to the contribution ceiling (Beitragsbemessungsgrenze), which is also adjusted annually — income above that ceiling is not subject to additional contributions.
The table below illustrates approximate monthly GKV contributions at different salary levels, using a combined rate of 15.6% (14.6% base plus a 1.0% example Zusatzbeitrag) as an illustration. Actual Zusatzbeitrag rates vary by fund.
Note: These figures are illustrative. The contribution ceiling and Zusatzbeitrag rates change annually. Always verify current figures with your chosen fund.
PKV premium drivers
Private premiums are set at the time of application and depend on:
- Age at entry — younger applicants lock in substantially lower premiums; this age-at-entry effect is one of the strongest arguments for joining PKV early if you qualify.
- Health status — pre-existing conditions can lead to surcharges, exclusions, or in some cases refusal of standard tariffs (though the Basistarif cannot reject applicants).
- Coverage level — tariff options range from near-GKV equivalents to comprehensive plans with private hospital rooms, dental, and optical.
- Deductible choice (Selbstbehalt) — a higher deductible lowers your monthly premium.
Pro Tip: When an employee chooses PKV, employers must contribute 50% of the monthly premium up to a defined maximum — effectively half of the average statutory contribution. Always calculate your net employee cost after this subsidy before comparing PKV to GKV on price alone. The raw PKV premium figure overstates what you actually pay.
4. What GKV covers versus what PKV can offer
Both systems cover the fundamentals. The differences show up in speed, comfort, and breadth.
Standard GKV benefits
Public health insurance covers a broad range of services, and GKV members typically pay little or nothing at the point of care. The mandatory benefit catalog includes:
- General practitioner and specialist consultations
- Hospital treatment (shared room, standard care)
- Prescription medications (with a standard co-payment of €5–€10 per prescription, capped annually)
- Preventive care and screenings
- Mental health treatment
- Maternity care and childbirth
- Physiotherapy and rehabilitation (with referral)
- Basic dental care (more extensive work requires co-payment or supplemental cover)
Co-payments are capped at 2% of annual gross income per year (1% for people with chronic conditions), which protects against catastrophic out-of-pocket costs.
What PKV typically adds
| Coverage area | GKV standard | PKV typical extras |
|---|---|---|
| Hospital room | Multi-bed ward | Single or double room, choice of consultant |
| Specialist access | Referral often required | Direct access, shorter wait times |
| Dental | Basic restorations covered | Higher-grade restorations, implants, orthodontics |
| Optical | Not routinely covered | Glasses and contact lens allowances in many tariffs |
| Mental health | Covered, but wait times vary | Faster access to psychotherapy in many tariffs |
| Maternity | Fully covered | Additional midwife visits, private room options |
| Reimbursement model | Direct billing to fund | You pay, then submit receipts for reimbursement |
For a detailed breakdown of what private tariffs typically include, Myhealthcarebroker's coverage explainer walks through common inclusions and exclusions in plain English.
Family coverage: the critical difference
In GKV, your non-earning or low-earning spouse and your children are co-insured at no extra cost — a significant benefit for families. In PKV, every family member requires a separate premium. For a family of four where only one parent works, PKV can cost considerably more than GKV once you add up individual premiums for a partner and two children. This is one of the most common reasons families with children stay in or return to GKV even when the employed parent qualifies for PKV.
5. How to enroll in German health insurance step by step
The enrollment process differs depending on your situation. Here is how each main path works.
For employees
- Confirm your income level against the current mandatory insurance threshold before your start date.
- Choose a statutory fund if you are below the threshold (or wish to stay in GKV voluntarily). Notify your employer of your chosen fund — they handle the registration with that fund on your behalf.
- Apply for PKV directly if you are above the threshold and want private cover. You will need to complete a health declaration and submit supporting documents to the insurer.
- Inform your employer of your PKV membership so they can calculate and pay their contribution share.
- Receive your insurance card (eGK for GKV, or a membership confirmation letter for PKV). GKV cards typically arrive within one to two weeks of registration.
For students
Students at German universities generally enroll in the student GKV tariff, which carries a reduced contribution rate. EU students with a valid European Health Insurance Card (EHIC) may be able to use home-country coverage for short periods, but most non-EU international students must enroll in German GKV or an approved private student plan from day one. Check with your university's student services office for the specific deadline — many require proof of cover before you can complete enrollment.
For students considering private options, Myhealthcarebroker's student insurance page outlines the available tariffs and eligibility rules.
For self-employed and freelancers
Self-employed people are not subject to compulsory GKV, but they must still carry coverage. The private health insurance application process for freelancers involves:
- Gathering proof of self-employment status (trade registration or freelance contract).
- Completing a health questionnaire for PKV underwriting.
- Submitting income documentation if applying for voluntary GKV.
- Confirming coverage start date aligns with your visa or residence permit application.
Documents you will need for any enrollment:
- Valid passport or national ID
- Employment contract or proof of self-employment
- Proof of prior insurance (if applicable)
- Residence registration certificate (Anmeldebestätigung) — or at minimum your address in Germany
- Visa or residence permit (or application confirmation)
Visa and immigration proof
Immigration offices expect a specific document: either a GKV membership confirmation or a PKV coverage certificate (Versicherungsnachweis). A US insurance card or a travel policy confirmation is not sufficient for a long-term residence permit application in most cases.
6. How to decide between GKV and PKV
The right system depends on your specific circumstances. Here is a practical framework.
Questions to work through before choosing PKV
- What is your income, and will it stay above the threshold? If your income fluctuates (common for freelancers), a year below the threshold can force you back into GKV.
- Do you have a non-earning partner or children? Free family co-insurance in GKV can outweigh PKV's benefit extras for families.
- How old are you? The age-at-entry effect in PKV is real: a 28-year-old can lock in a premium that a 45-year-old cannot.
- Do you have pre-existing conditions? PKV underwriting can exclude conditions or add surcharges. GKV cannot.
- How long do you plan to stay in Germany? PKV premiums rise with age, and returning to GKV after 55 is severely restricted.
- What are your retirement plans? GKV pensioner contributions are income-based; PKV premiums in retirement can be substantial if you did not build adequate aging reserves.
Scenario mapping
| Scenario | Typically better fit | Key reason |
|---|---|---|
| Single, high earner, no dependants | PKV | Lower entry premium, richer benefits, employer subsidy |
| Family with children, one income | GKV | Free co-insurance for partner and children |
| Self-employed freelancer, healthy, age 30 | PKV | No compulsory GKV; age-at-entry advantage |
| Civil servant (Beamter) | PKV | State Beihilfe subsidy makes PKV the standard |
| Employee near retirement, pre-existing conditions | GKV | Stable income-based contributions, no underwriting |
| Student | GKV student tariff | Low contribution rate, straightforward enrollment |
The public vs. private comparison guide at Myhealthcarebroker goes deeper on each scenario with current threshold figures.
A note on PKV tariff questions to ask before signing:
- Does the tariff include aging reserves (Alterungsrückstellungen) to moderate future premium increases?
- What is the Basistarif premium if standard tariffs become unaffordable later?
- Are there waiting periods for pre-existing conditions, and how long?
- What is the insurer's track record on premium stability over the past five years?
7. Switching between GKV and PKV: rules and real risks
Switching systems is not as simple as changing banks. The rules are asymmetric, and the consequences of a wrong move can follow you for decades.
Moving from GKV to PKV
An employee can switch to PKV once their income has exceeded the mandatory insurance threshold for a full calendar year (or is contractually guaranteed to do so). The switch typically takes effect at the start of the following month after giving notice to the GKV fund, usually with a two-month notice period.
For a step-by-step walkthrough of the paperwork and timing, Myhealthcarebroker's switching guide covers the process in English.
Moving from PKV back to GKV
This is where many people get caught. Returning to GKV is only straightforward if:
- Your income drops below the mandatory insurance threshold (e.g., you take a lower-paying job).
- You become unemployed and claim benefits.
- You are under 55 and re-enter employment below the threshold.
Switching back into GKV can be restricted after age 55 — a constraint that catches many people who chose PKV in their 30s and later want the stability of income-based contributions in retirement. After 55, the only reliable route back to GKV is through unemployment or a significant income drop, and even then it is not guaranteed.
Common switching pitfalls:
- Long-term premium creep in PKV: Premiums rise with age and medical inflation. Without adequate aging reserves built into your tariff, costs in your 50s and 60s can rise sharply.
- Loss of family co-insurance: Once you leave GKV, your dependants lose free co-insurance and need their own PKV policies.
- Self-employed income volatility: A year below the threshold can force a return to GKV, and re-entering PKV later at an older age means higher premiums.
- Mid-year switching restrictions: Changing funds within GKV mid-year is possible but requires a minimum membership period. Timing your switch correctly matters for avoiding gaps.
8. Using U.S. health insurance in Germany: what actually works
The short answer: your US plan almost certainly does not work for long-term residence in Germany.
US domestic health plans are designed for the American market. They do not meet German legal requirements for residents, do not cover German providers on a direct-billing basis, and will not satisfy immigration authorities when you apply for a residence permit. Long-term residents and workers must enroll in a German-compliant GKV or recognized PKV plan — there is no workaround for this.
Short-term travel insurance occupies a narrow but real exception. For initial visa applications (particularly for job-seeker visas or short-stay visas), some immigration offices accept a travel insurance policy as temporary proof of coverage; however, this is a bridge, not a solution. Once you establish residency and begin employment, you must transition to a German-compliant plan.
| Coverage type | Visa proof (short-stay) | Long-term residency | Employment in Germany |
|---|---|---|---|
| US domestic health plan | Generally not accepted | Not accepted | Not accepted |
| Short-term travel insurance | Sometimes accepted (check with consulate) | Not accepted | Not accepted |
| German GKV membership | Accepted | Accepted | Required if below threshold |
| German PKV (recognized insurer) | Accepted | Accepted | Required if above threshold and choosing PKV |
Pro Tip: If you are arriving on a freelance visa (Freiberufler-Visum) or a job-seeker visa, secure a short-term travel policy with at least €30,000 coverage for the initial application, then transition to a German-compliant plan within the first weeks of arrival. Myhealthcarebroker's expat insurance page explains which temporary policies are typically accepted and how to make the transition without a coverage gap.
9. Practical arrival checklist for U.S. residents moving to Germany
Getting your insurance sorted quickly after arrival is not just about health protection — it unlocks your tax ID, your bank account, and your residence permit. Here is the sequence that works.
Immediate steps on arrival
- Register your address (Anmeldung) at the local residents' registration office (Einwohnermeldeamt) within 14 days of arrival. You need this address registration before most insurance applications can be completed.
- Confirm your insurance enrollment with your employer's HR department (for employees) or submit your PKV application directly (for self-employed). Do not wait — coverage gaps can create legal and financial problems.
- Receive your tax ID (Steueridentifikationsnummer), which is mailed to your registered address and typically arrives within two to four weeks.
- Obtain your electronic health insurance card (eGK) from your GKV fund, or your PKV membership certificate. The eGK is your access card for GP and specialist visits.
- Verify family enrollment if you have a partner or children. Confirm with your GKV fund that dependants are correctly co-insured, or submit separate PKV applications for each family member.
If coverage verification is delayed
GKV funds can take one to two weeks to issue the physical eGK. In the meantime, ask your fund for a temporary proof of membership letter (vorläufige Versicherungsbescheinigung) — most providers and pharmacies accept this.
Common mistakes to avoid:
- Assuming your US employer's international health plan satisfies German legal requirements. It almost never does.
- Waiting until after your first paycheck to enroll. GKV coverage is retroactive to your employment start date, but gaps in PKV can be harder to resolve.
- Forgetting to check whether your partner qualifies for free GKV co-insurance or needs a separate policy.
- Not comparing Zusatzbeitrag rates across GKV funds. The base rate is fixed, but the surcharge varies, and switching funds is straightforward if you do it at the right time.
- Applying for PKV without a health declaration review. Undisclosed pre-existing conditions can void coverage or lead to contract disputes later.
10. When a specialist broker makes the difference
Navigating German health insurance in a second language, under time pressure, while also managing a relocation, is genuinely difficult. A specialist broker does not just save you time — they reduce the risk of making a choice you cannot easily undo.
The value shows up most clearly in three situations. First, if you are a high earner deciding between GKV and PKV for the first time: the premium comparison, employer subsidy calculation, and tariff selection involve enough variables that a broker who does this daily will reach a better answer faster than you will alone. Second, if you have a complex health history: a broker who knows which PKV insurers apply lighter underwriting for specific conditions can steer you toward a tariff that accepts you on reasonable terms, rather than leaving you to discover exclusions after signing. Third, if you are insuring a family: the free co-insurance calculation in GKV versus the cumulative PKV premium for a partner and children is not always obvious, and getting it wrong is expensive.
What a broker can do: run an independent eligibility check, compare tariffs across all major PKV insurers, handle the application in English, and support you through the process at no cost to you (brokers in Germany receive a regulated commission from the insurer). What a broker cannot do: override legal eligibility rules or guarantee PKV acceptance if your health history triggers underwriting concerns.
Myhealthcarebroker helps you get it right from the start
Sorting out German health insurance as a US expat means navigating a system built in German, governed by rules that change annually, and structured around categories that do not map neatly onto American experience. Myhealthcarebroker cuts through that.
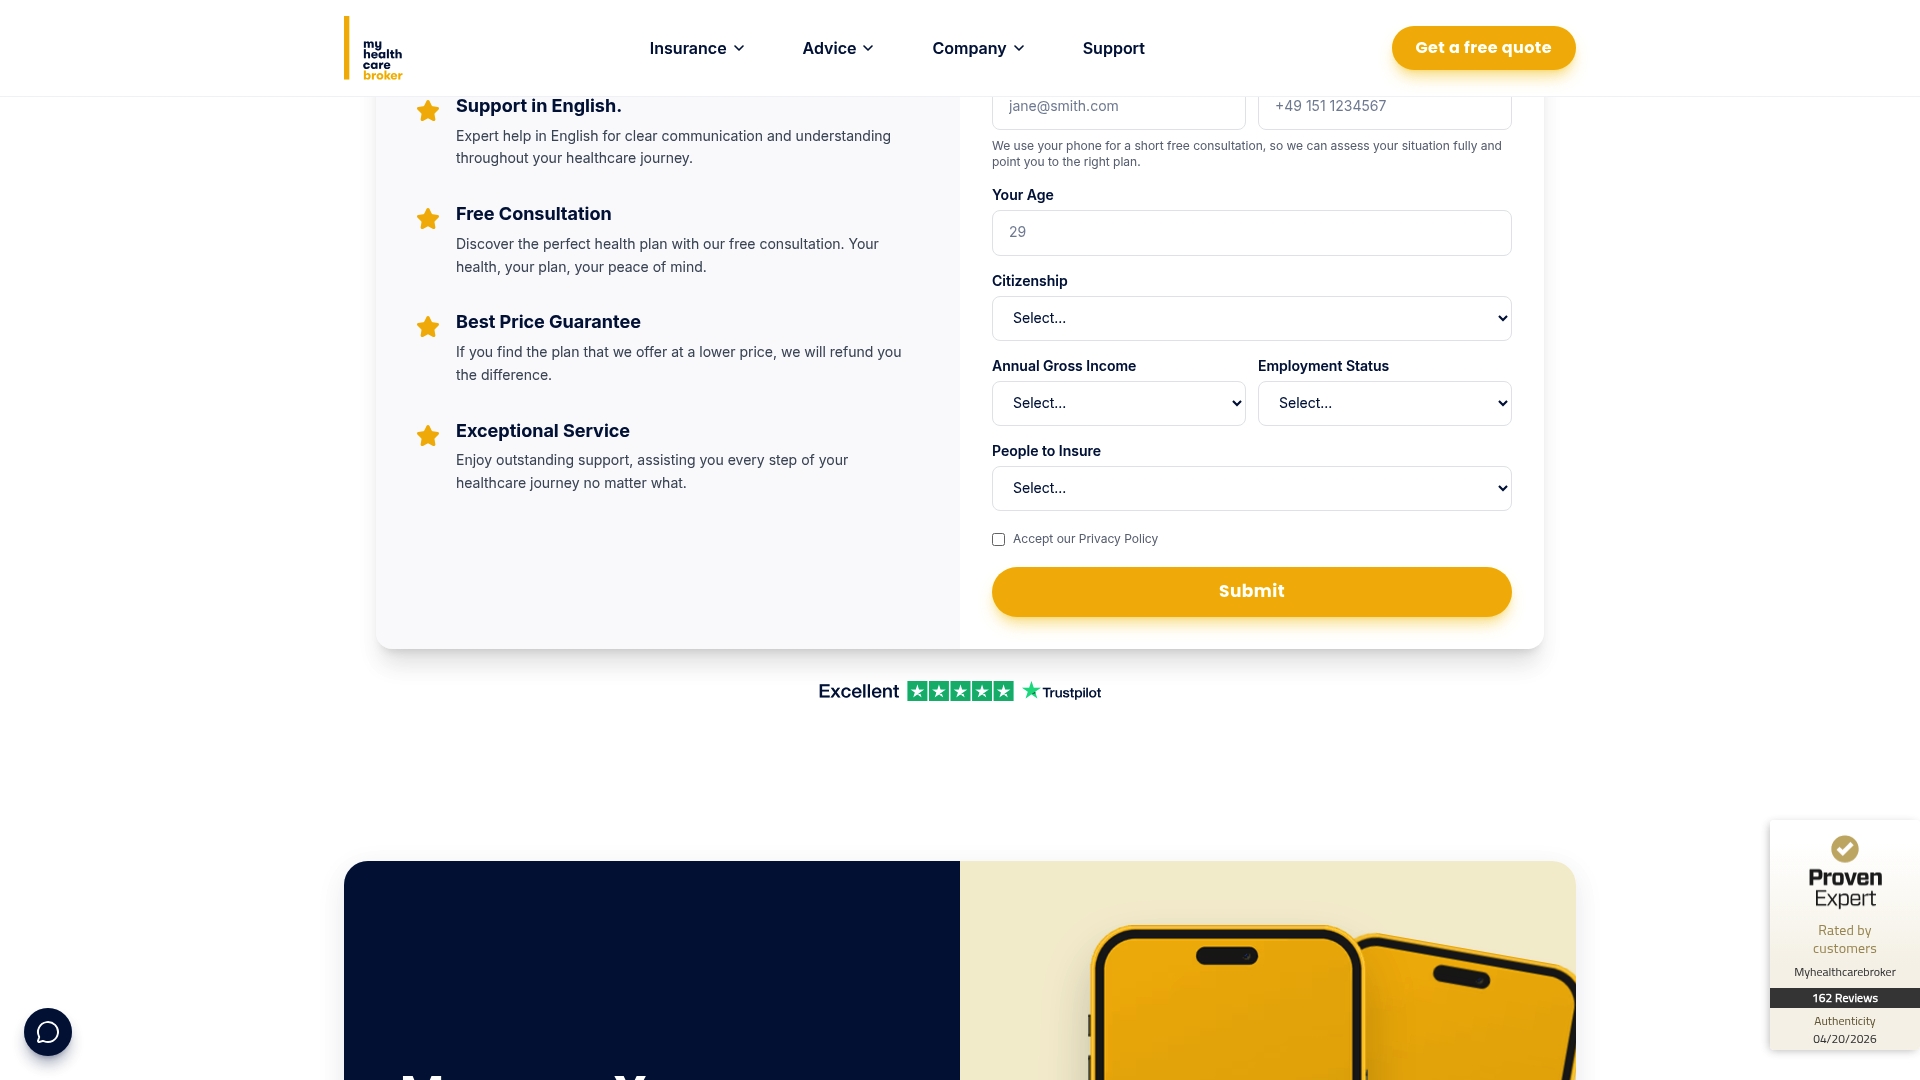
As an independent broker, Myhealthcarebroker compares PKV tariffs across all major German insurers and guides you to the plan that genuinely fits your situation — in clear English, with no jargon and no pressure. The service covers everything from your first eligibility check to the completed application and ongoing support afterward. For employees weighing PKV against GKV, the private health insurance calculator gives you a real cost estimate including the employer subsidy, so you can compare on net cost rather than headline premiums. For those who need full-service support, the English-language PKV advice page explains exactly how the process works. The service is free to you — Myhealthcarebroker receives a regulated commission from the insurer when you sign up. Start with a free eligibility check at Myhealthcarebroker and know where you stand before you commit to anything.
An honest perspective on the GKV vs. PKV decision
Most articles about German health insurance frame the GKV vs. PKV choice as a straightforward income calculation. Earn above the threshold, choose PKV, save money. That framing is not wrong, but it is incomplete in ways that matter.
The real issue is that PKV is a long-term financial product masquerading as an annual insurance decision. When you sign up at 30, you are not just choosing coverage for next year — you are making a bet on your income trajectory, your health, your family plans, and your retirement strategy for the next 40 years. The age-at-entry premium advantage is genuine, but it only stays an advantage if your income remains above the threshold, your health stays insurable at standard rates, and you build adequate aging reserves to absorb premium increases in your 50s and 60s.
The families-with-children calculation is the one most commonly underestimated. I have seen high earners choose PKV for themselves, then realize six months later that insuring a partner and two children privately costs more per month than the GKV alternative would have. The free co-insurance rule in GKV is not a minor footnote — for a family of four on one income, it can be worth several hundred euros a month.
The other underappreciated risk is the post-55 return restriction. Germany's rule that makes it very difficult to return to GKV after age 55 is not widely discussed in expat forums, but it is one of the most consequential features of the system. If you choose PKV at 35 and your circumstances change at 52 — a health event, a career shift, a divorce — your options narrow significantly. That asymmetry deserves more weight in the initial decision than most people give it.
None of this means PKV is the wrong choice. For a healthy, high-earning single professional in their late 20s or early 30s with no plans for children, it often is the right one. The point is that the decision warrants a proper analysis, not a quick income comparison.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
The following official and authoritative sources were used in this article. They are the best starting points for verifying current thresholds, contribution rates, and enrollment rules:
- Statutory health insurance (SHI) | BMG
- Gesund
- Health care in Germany: Learn More – Health insurance in Germany (NCBI Bookshelf)
- Statutory and private health insurance: the differences explained | TK
- Migration-gesundheit
- Private Krankenversicherung | ARAG
For enrollment questions, always cross-reference with the official source for your specific category (employee, student, self-employed, or civil servant) and confirm current threshold figures directly with a statutory fund or a qualified broker, as rates and ceilings are updated annually.