For most employees with a partner or children, Germany's statutory system (GKV, or gesetzliche Krankenversicherung) is the better default. Private health insurance (PKV, or private Krankenversicherung) tends to be cheaper and more benefit-rich for young, healthy high earners, civil servants, and the self-employed — but it comes with real long-term risks that catch people off guard.
Here are the two most common starting points:
- GKV is usually the right fit for: employees earning below the Jahresarbeitsentgeltgrenze (JAEG) per year, families with a non-earning partner or children, and anyone who values predictable contributions tied to income rather than age. Techniker Krankenkasse (TK) and DAK-Gesundheit are two of the largest GKV funds and give you a sense of the standardized benefit package available across the statutory system.
- PKV is worth modeling if: you earn above €77,400 gross per year as an employee, you are self-employed or a civil servant (Beamter), you are young and in good health, and you have no dependents who would need separate PKV contracts.
If you are not sure which category you fall into, Myhealthcarebroker offers a free eligibility check in English that applies the current JAEG and Beitragsbemessungsgrenze (BBG) thresholds to your actual situation before you commit to anything.
Table of Contents
- How does the GKV vs PKV system actually work?
- What do you actually get? GKV vs PKV benefits compared
- How are GKV and PKV costs calculated?
- Who can choose PKV, and what are the rules for your group?
- How does family coverage work, and why does it change the math?
- When can you switch to PKV, and how hard is it to return to GKV?
- What are the long-term risks, and how do you plan for them?
- A practical checklist to decide for your own situation
- How Myhealthcarebroker runs an eligibility check: a worked example
- When is GKV cheaper, and when can PKV actually cost less?
- Key Takeaways
- Why a personalized eligibility check matters more than any general rule
- Myhealthcarebroker: free eligibility check and English-language PKV comparison
- Useful sources and tools to verify thresholds and run your own scenarios
How does the GKV vs PKV system actually work?
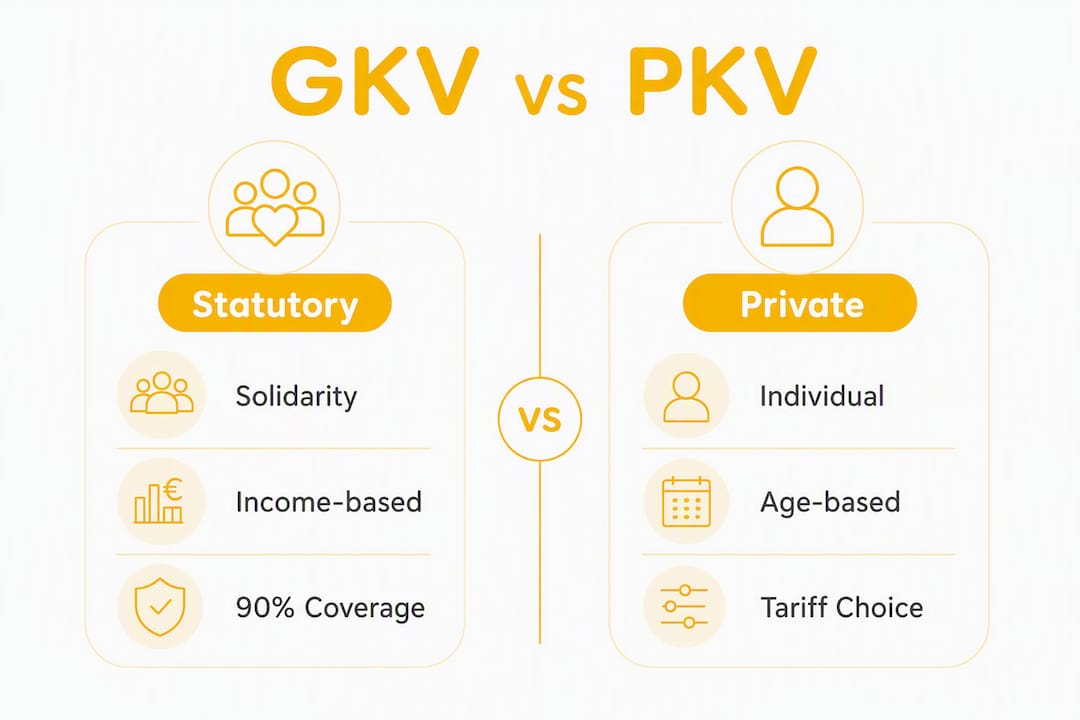
The single most important structural difference: GKV is built on solidarity (everyone contributes according to income, everyone gets the same statutory benefits), while PKV is built on equivalence (your premium reflects your personal risk profile at the time you apply).
The statutory system (GKV)
GKV covers roughly 90% of people in Germany. Contributions are calculated as a percentage of your gross income, capped at the BBG. Every GKV fund must provide the same core statutory benefits defined in the Sozialgesetzbuch V (SGB V). Funds like Techniker Krankenkasse may add voluntary extras on top, but the statutory floor is identical across all roughly 90 funds. Your entitlement is legal, not contractual — it cannot be reduced by an insurer's business decision.
The private system (PKV)
PKV premiums are set at the time you apply, based on your age, health status, and the tariff you choose. Benefits are contractually defined in your policy, not set by law. That distinction matters: the Bundesgesundheitsministerium notes that PKV insurers build aging reserves (Altersrückstellungen) to cushion future premium increases, but premiums can still rise significantly over time and are never tied to your income.
| Dimension | GKV (statutory) | PKV (private) |
|---|---|---|
| Guiding principle | Solidarity — income-based contributions | Equivalence — risk/age-based premiums |
| Who pays and how | Employee + employer split; capped at BBG | Individual pays based on tariff and health at entry |
| How benefits are determined | Statutory (SGB V) — legally guaranteed | Contractual — defined in your policy tariff |
What do you actually get? GKV vs PKV benefits compared
PKV tends to offer contractually guaranteed extras; GKV covers a standardized statutory package that is legally protected but politically subject to reform.
Standard GKV benefits
Every GKV member receives the same core package, regardless of which fund they join:
- Doctor visits and specialist referrals (GP referral usually required for specialists)
- Hospital treatment in a shared room with the attending ward doctor
- Prescription medications (co-payments apply, capped annually)
- Preventive care, cancer screenings, and vaccinations
- Mental health treatment and psychotherapy
- Maternity care and midwife services
- Dental treatment at standard rates (higher-grade work requires top-up payments)
- Sick pay (Krankengeld) after six weeks of employer-paid sick leave
Typical PKV extras
Private tariffs vary widely, but higher-tier PKV plans commonly include:
- Direct specialist access without a GP referral
- Single or double room in hospital (Einbettzimmer/Zweibettzimmer)
- Treatment by the chief physician (Chefarztbehandlung)
- Shorter waiting times for appointments
- Higher dental reimbursement rates (often 80–100% for crowns and implants)
- Optical benefits (glasses, contact lenses)
- Alternative medicine and naturopathic treatments
- Broader mental health coverage and private psychotherapy
The critical distinction is what happens when things change. GKV benefits are set by law, so they apply uniformly — but parliament can reduce them through reform. PKV benefits are locked into your contract, so an insurer cannot unilaterally remove a covered service, but they can raise premiums to maintain the same benefit level.
Pro Tip: When reading a PKV tariff, check three things before anything else: the reimbursement rate (is it 100% of the fee schedule, or capped at a multiplier?), the waiting period for pre-existing conditions, and whether the tariff includes a benefit-reduction clause if you make frequent claims. These three items explain most of the gap between what a PKV brochure promises and what you actually receive.
How are GKV and PKV costs calculated?
GKV contributions scale with your income; PKV premiums scale with your age and health at the time you apply. That one sentence explains why PKV can be cheaper when you are young and healthy, and why it can become expensive as you age.
GKV calculation mechanics
Your GKV contribution is based on gross income up to the BBG. The general contribution rate is 14.6%, split equally between you and your employer (7.3% each). On top of that, each fund charges a supplemental contribution (Zusatzbeitrag) — the average in 2026 is roughly 2.9%, also split 50/50. So the effective total rate is approximately 17.5%, with you paying about 8.75% and your employer matching that.
The BBG for 2026 is €69,750 per year. If you earn more than that, your GKV contribution is capped — you pay no more regardless of how high your salary goes.
PKV calculation mechanics
PKV premiums depend on your entry age, your health status at application (underwriting), and the tariff you select. You can reduce premiums by choosing a higher deductible (Selbstbehalt). Premiums are not split with your employer in the same way — instead, your employer contributes up to a capped amount (roughly €508.59/month in 2026), and you pay any difference above that yourself.
Worked cost scenarios
| Profile | GKV monthly contribution (approx.) | PKV monthly premium (approx.) | Key driver |
|---|---|---|---|
| Single employee, age 35, €80,000 gross/year | ~€508.59 (capped at BBG) | €350+ depending on tariff | PKV competitive; employer subsidy covers most of it |
| Married, one earner, €80,000, two children | ~€508.59 (family covered free) | ~€900+ (four separate contracts) | GKV significantly cheaper for families |
| Self-employed, age 30, moderate income | ~€875 (full rate, no employer share) | €400+ (no employer subsidy) | PKV often cheaper; self-employed pay full GKV rate |
These ranges are illustrative. For accurate 2026 cost figures based on your actual income and tariff choices, use a personalized calculator.
One more thing worth noting on long-term cost trends: industry data show that between 2006 and 2026, GKV per-capita costs rose at an average of roughly 3.9% per year, while PKV premiums rose at roughly 3.4% per year on average. However, 2026 PKV projections show many tariffs experiencing adjustments of 9–18% for a notable share of policyholders — well above the long-run average. That gap between the historical average and the current year's adjustments is exactly why long-term scenario modeling matters.
Who can choose PKV, and what are the rules for your group?
The default in Germany is GKV for most employees. You can only opt into PKV if you meet specific eligibility criteria — and the rules differ significantly by employment status.
The single-sentence rule for employees: you must earn above the JAEG (€77,400 gross per year in 2026) for at least one consecutive year before you can opt out of GKV and into PKV.
Eligibility by group
- Employees above the JAEG: Eligible to choose PKV after meeting the income threshold for a full year. You have a limited window (typically three months after your salary crosses the threshold) to declare your intention to switch.
- Self-employed and freelancers: Not subject to mandatory GKV enrollment. You can choose PKV from day one of self-employment, regardless of income. The trade-off is that you pay the full PKV premium yourself with no employer subsidy.
- Civil servants (Beamte): The most straightforward PKV case. The state covers a portion of medical costs through Beihilfe (typically 50–70%), and PKV covers the remainder. GKV is rarely cost-competitive for civil servants.
- Students: Mandatory student GKV applies while enrolled, at reduced contribution rates. Student GKV contributions run around €127/month for younger students. Once you exceed the age limit or change status, you must move to voluntary GKV or evaluate PKV eligibility separately. For students considering PKV, Myhealthcarebroker has a dedicated student private health insurance guide.
- Expats and international professionals: The default is GKV unless you meet the JAEG threshold. Many expats assume they can freely choose PKV — in practice, the income gate applies just as it does for German employees.
Eligibility checklist
- Confirm your gross annual income against the 2026 JAEG of €77,400.
- Gather your last 12 months of payslips and your current employment contract.
- Check whether your employer has confirmed your salary in writing.
- Verify your family status (partner's income, number of children).
- Note any pre-existing health conditions that could affect PKV underwriting.
- Confirm your current GKV fund's notice period (usually three months to end of the calendar year).
The decision window after a salary increase that crosses the JAEG is typically three months. Miss it, and you stay in GKV for another year.
How does family coverage work, and why does it change the math?
GKV offers free family coverage for non-earning spouses and children under qualifying conditions; PKV charges a separate premium for every family member. That single rule shifts the cost comparison dramatically for families.
Under GKV, a non-earning spouse and any number of children are covered at no additional cost, provided the spouse earns below a low income threshold and is not independently insured. Under PKV, each family member requires their own contract and their own monthly premium.
Family cost comparison: one-earner household
| Family setup | GKV monthly cost (approx.) | PKV monthly cost (approx.) |
|---|---|---|
| Employee above JAEG, non-earning partner, two children | ~€508.59 (all four covered) | ~€900+ (four separate contracts) |
| Civil servant with Beihilfe, same family | GKV rarely chosen | ~€400+ after Beihilfe subsidy |
The numbers above use the 2026 threshold and family premium data as a guide. Actual PKV premiums for children often run €100–€200 per child per month depending on the tariff.
Decision hint by family profile:
- Families with a non-earning partner and children: GKV is almost always cheaper. The free family coverage benefit is substantial and hard to replicate in PKV.
- Civil servants (Beamte) with families: PKV with Beihilfe often remains competitive even with children, because the state subsidy covers a large share of costs.
- Dual high earners, no children: Both partners may be PKV-eligible, and the family coverage argument disappears. PKV can make sense for both.
When can you switch to PKV, and how hard is it to return to GKV?
Switching to PKV is permitted for eligible groups, but returning to GKV later is strictly limited — especially after age 55. That asymmetry is the most important practical fact about the German health insurance system.
Step-by-step switch checklist
- Verify eligibility: Confirm you meet the JAEG threshold (€77,400 in 2026) or qualify through self-employment, civil service, or student status.
- Get PKV quotes: Obtain at least two tariff quotes (one basic, one mid-range) to model the cost range. Myhealthcarebroker's PKV application guide walks through the paperwork in detail.
- Complete medical underwriting: Answer the health questionnaire honestly. Pre-existing conditions can lead to premium loadings, benefit exclusions, or outright refusal. If you are refused standard market tariffs, a minimum "Basistarif" exists as a backstop, but it is not equivalent to a full private tariff.
- Give notice to your GKV fund: The standard notice period is three months to the end of a calendar month. Check your specific fund's rules.
- Declare to your employer: Notify your employer so they can adjust their contribution to the PKV subsidy (capped at roughly €508.59/month in 2026).
- Confirm PKV start date: Coordinate so there is no gap in coverage.
Switching windows and return conditions
| Scenario | Typical window | Return to GKV possible? |
|---|---|---|
| Employee crosses JAEG threshold | 3 months after threshold is met | Yes, if income drops below JAEG again |
| Self-employed returns to employment below JAEG | On employment start date | Yes, mandatory re-enrollment |
| Age 55+, long-term PKV policyholder | No standard window | Heavily restricted — legal pathways are very limited |
| Income drops below JAEG (employee) | Immediately on income change | Yes, mandatory GKV re-enrollment |
Common mistakes that create long-term lock-in:
- Switching to PKV at age 35–40 without modeling what premiums look like at 60 or 65.
- Assuming you can return to GKV whenever you want — the age-55 restriction is real and catches people off guard.
- Ignoring the family cost impact when planning to have children after switching.
- Skipping a detailed comparison of at least two tariff levels before committing.
What are the long-term risks, and how do you plan for them?
Long-term premium evolution is the decisive risk factor in the GKV vs PKV decision. Both systems have seen costs rise over time, but the mechanisms and risks are different.
In GKV, your contribution rises only if your income rises or if the contribution rate increases through legislation. In PKV, your premium can rise independently of your income — driven by medical cost inflation, your insurer's claims experience, and the aging of the insured pool.
PKV insurers are legally required to build aging reserves (Altersrückstellungen) to partially offset future premium increases. These reserves are a genuine consumer protection, but they do not eliminate premium growth. They also cannot be transferred in full if you switch PKV insurers, which creates a degree of lock-in within the private system as well.
Statistic callout: Industry data covering 2006–2026 show average annual premium changes of roughly 3.4% for PKV and roughly 3.9% for GKV per insured. In 2026, however, many PKV tariffs are seeing adjustments of 9–18% for a notable share of policyholders — a sharp departure from the long-run average that underscores why single-year projections can mislead.
Practical planning steps
- Build three scenarios: what your PKV premium looks like in 3 years, 10 years, and 20 years, using a conservative annual increase assumption.
- Check whether your PKV tariff includes a buy-back option (Beitragsentlastungstarif) that lets you pay extra now to reduce premiums later.
- Ask your insurer for the past 10 years of premium adjustment history on the specific tariff you are considering — not the company average, the tariff.
- Verify your insurer's solvency rating and whether it is a mutual (Versicherungsverein auf Gegenseitigkeit) or stock company, since mutual structures tend to prioritize policyholder interests over shareholder returns.
Pro Tip: Before signing any PKV contract, ask the insurer directly: "What was the average annual premium increase for this specific tariff over the last 10 years?" A company that cannot or will not answer that question clearly is telling you something important about how it manages transparency.
For a deeper look at how PKV premiums are calculated and how aging reserves factor in, Myhealthcarebroker's dedicated cost guide covers the mechanics in plain English.
A practical checklist to decide for your own situation
Run a detailed comparison with real quotes whenever your gross income is within €10,000 of the JAEG, you are self-employed, or your family situation is about to change. Generic rules only take you so far.
What to gather before comparing
- Your gross annual income for the last 12 months (payslips or tax return).
- Your employment contract confirming your current salary.
- Your family status: partner's income, number of children, whether anyone has a pre-existing condition.
- Your age and general health history (relevant for PKV underwriting).
- Your employer's PKV subsidy cap confirmation (roughly €508.59/month in 2026).
- Your Beihilfe entitlement percentage if you are a civil servant.
- Your current GKV fund name and the Zusatzbeitrag it charges (the 2026 average is about 2.9%).
- Any career plans that might affect income stability over the next five years.
Questions to ask when speaking with an insurer or broker
- What is the exact reimbursement rate for specialist visits and hospital stays in this tariff?
- What pre-existing conditions would be excluded or loaded?
- What was the premium increase history for this specific tariff over the last 10 years?
- What happens to my aging reserves if I switch to a different PKV insurer?
- What are the conditions under which I could return to GKV?
How Myhealthcarebroker runs an eligibility check: a worked example
This is how we determine whether GKV or PKV is a practical option for a client — and what the numbers actually look like once we apply the current thresholds.
Anonymized case: expat software engineer, age 34
Profile: Single, no children, employed in Munich, gross salary €88,000/year, no significant pre-existing conditions, arrived in Germany 18 months ago and enrolled in GKV on arrival.
Data gathered: Last 12 months of payslips confirming salary above the 2026 JAEG of €77,400. Employment contract showing permanent position. No prior German insurance history beyond the current GKV enrollment. No dependents.
How we applied the thresholds:
| Input | Value | Implication |
|---|---|---|
| Gross annual salary | €88,000 | Above JAEG (€77,400) — PKV-eligible |
| BBG (2026) | €69,750/year | GKV contribution capped at this income level |
| GKV monthly contribution | ~€508.59 | Based on BBG cap + 17.5% effective rate |
| Employer PKV subsidy cap | ~€508.59/month | Covers most of a mid-range PKV tariff |
| PKV quote range (low tariff) | ~€320/month | After employer subsidy: minimal net cost |
| PKV quote range (mid tariff) | ~€480/month | After employer subsidy: minimal net cost |
Result: For this profile, a mid-range PKV tariff costs roughly the same out-of-pocket as GKV, while delivering direct specialist access, single-room hospital coverage, and higher dental reimbursement. The recommendation was to model two tariffs (low and mid) and build a 20-year premium projection before deciding.
What we did not do: recommend PKV automatically just because the client was eligible. We also modeled the scenario where the client's income drops below the JAEG (e.g., career change, parental leave), and noted the age-55 return restriction as a long-term planning factor.
Myhealthcarebroker is compensated by a regulated commission from the insurer when a client signs up through our service. The client pays nothing for the eligibility check, the comparison, or the application support.
When is GKV cheaper, and when can PKV actually cost less?
The cost winner depends almost entirely on your profile. Here is the scenario-by-scenario picture.
- Single, young, high earner (e.g., age 30–40, no children, earning above €77,400): PKV is often cheaper or comparable, especially with the employer subsidy covering most of the premium. The benefit package is also significantly better.
- Married with a non-earning partner and children: GKV wins on cost, often by several hundred euros per month. Free family coverage is a structural advantage that PKV cannot match unless Beihilfe is in play.
- Self-employed with variable income: PKV is frequently cheaper because the self-employed pay the full GKV rate with no employer share. A healthy 30-year-old self-employed person can often find a PKV tariff well below what GKV would cost. The risk is that income variability does not reduce PKV premiums — if income drops, the premium stays fixed.
- Civil servant with Beihilfe: PKV almost always wins. The state covers 50–70% of medical costs through Beihilfe, and PKV covers the rest. GKV is rarely competitive for this group.
Final decision hint: If your profile is clearly in one camp (a family with one earner, or a civil servant), the default answer is usually right. If you are near the JAEG threshold, self-employed, or planning a major life change, run the numbers with real quotes before accepting the default. A public vs private health insurance comparison with current figures is the fastest way to see where you stand.
Key Takeaways
Choosing between Germany's statutory and private health insurance systems is a long-term financial decision, not a short-term cost comparison — family status, age, career stability, and the near-irreversibility of switching after 55 all carry as much weight as the monthly premium.
| Point | Details |
|---|---|
| JAEG threshold is the employee gate | Employees must earn above the gross/year threshold before they can opt into PKV. |
| Family coverage changes the math | GKV covers non-earning spouses and children for free; PKV charges separate premiums per person, often adding €100–€200/month per child. |
| Returning after 55 is very difficult | Legal pathways back to GKV are heavily restricted once you are over 55 and have been in PKV long-term. |
| PKV premiums can spike in any given year | The 2006–2026 average PKV increase was roughly 3.4%/year, but 2026 saw many tariffs adjusting 9–18% for a notable share of policyholders. |
| Myhealthcarebroker offers a free eligibility check | Independent English-language comparison across major insurers, with no cost to the client. |
Why a personalized eligibility check matters more than any general rule
Generic rules about GKV and PKV get you about 80% of the way there. The remaining 20% is where most people make expensive mistakes.
The most common one: assuming that because PKV looks cheaper today, it will stay cheaper. Premium projections over 20 or 30 years are genuinely uncertain, and the 2026 adjustment cycle is a reminder that above-average years happen. The second most common mistake is switching to PKV without fully accounting for family plans — a decision that makes sense at 32 as a single person can look very different at 38 with two children.
What actually helps is a comparison built on your specific numbers: your income, your age, your health history, your family situation, and at least two tariff scenarios. Generic online calculators give you a starting point. A conversation with an independent broker who applies the current JAEG and BBG thresholds to your actual payslips gives you a decision you can stand behind.
Myhealthcarebroker's approach is to run the eligibility check first, then model at least two PKV tariffs (one conservative, one mid-range) alongside the GKV baseline, and present the comparison in plain English without pushing a particular outcome. The commission structure means we are paid only when a client signs up for a policy — so there is no incentive to recommend PKV when GKV is the better fit, and no fee to the client either way.
One thing worth stating plainly: the legal restrictions on returning to GKV after age 55 are not a technicality. They are a structural feature of the system that affects real people who switched in their 30s without a fallback plan. Any honest comparison has to put that front and center.
Myhealthcarebroker: free eligibility check and English-language PKV comparison
Navigating the GKV vs PKV decision in a second language, against a backdrop of annual threshold changes and complex underwriting rules, is genuinely difficult. Myhealthcarebroker cuts through that by giving you a clear, personalized answer in English — at no cost to you.
The service covers everything from the first eligibility check to the final application:
- Eligibility check: We apply the current JAEG and BBG thresholds to your income and employment situation to confirm whether PKV is actually an option for you.
- Tailored quotes: We compare tariffs across major German private insurers and present at least two scenarios (conservative and mid-range) so you can see the cost range, not just a single number.
- Application support: We handle the paperwork, coordinate with the insurer, and guide you through medical underwriting in plain English.
Myhealthcarebroker receives a regulated commission from the insurer when you sign up through our service. You pay nothing for the comparison, the advice, or the application support.
Ready to see whether PKV makes sense for your situation? Use the private health insurance calculator to get an instant estimate, or visit the private health insurance in Germany page to book a free eligibility check with an English-speaking adviser.
Useful sources and tools to verify thresholds and run your own scenarios
Official sources update their figures annually. Always check the primary source before making a coverage decision.
- Bundesgesundheitsministerium (BMG) — Ratgeber Krankenversicherung — The federal health ministry's official guide to both GKV and PKV. Best for understanding the legal framework, SGB V, and the principles behind each system.
- MS in Germany — Health Insurance Decision Tool — An English-language decision tool that walks through GKV vs PKV eligibility with current figures. Useful for a quick first-pass check.
- Myhealthcarebroker — Private Health Insurance Calculator: Run a personalized GKV vs PKV cost scenario using your actual income and family situation.
- Myhealthcarebroker — Public vs Private Health Insurance in Germany: The broker's comparative overview page, with current thresholds and English-language application support.
| Source | Best used for |
|---|---|
| BMG Ratgeber Krankenversicherung | Legal framework, SGB V, system principles |
| BMG Wechsel page | Current JAEG threshold, switching and return conditions |
| MS in Germany decision tool | Quick English-language eligibility check |
| Wegweiser Gesundheit | Newcomer/expat orientation, GKV fund examples |
| Myhealthcarebroker calculator | Personalized cost scenarios with 2026 figures |
| Myhealthcarebroker landing page | Broker comparison, English-language application support |
This article provides general information about the German health insurance system. It is not legal or financial advice. Thresholds and rates change annually — confirm current figures with the BMG or a qualified adviser before making a coverage decision.