The Versicherungspflichtgrenze, formally known as the Jahresarbeitsentgeltgrenze (JAEG), is the annual gross income threshold that gives employees in Germany the legal right to leave statutory health insurance (GKV) and choose private health insurance (PKV) instead. Cross it, and you gain a genuine choice. Stay below it, and GKV membership remains compulsory. Für 2026 liegt die Versicherungspflichtgrenze (JAEG) bei 77.400 € brutto jährlich; dieser Wert wurde durch die Sozialversicherungs-Rechengrößenverordnung festgelegt.
Table of Contents
- How the threshold is set and what's changing in 2027
- Who can actually opt for private insurance?
- What counts toward your annual working remuneration?
- Key dates and deadlines you need to know
- What switching to PKV actually means for you
- Exceptions and special cases that change the picture
- Your checklist when your salary crosses the threshold
- Key Takeaways
- The decision most people get wrong
- How Myhealthcarebroker helps you navigate this decision
- Useful sources
How the threshold is set and what's changing in 2027
The JAEG isn't a fixed number. It adjusts each year based on the development of gross wages and salaries per employee from prior calendar years, then gets formalized in the Sozialversicherungs-Rechengrößenverordnung. Think of it as a wage-indexed moving target: when average salaries rise across Germany, the threshold rises with them.
For 2026, the official figure announced by authorities is used by employers to determine whether you're subject to compulsory GKV membership or free to choose PKV.
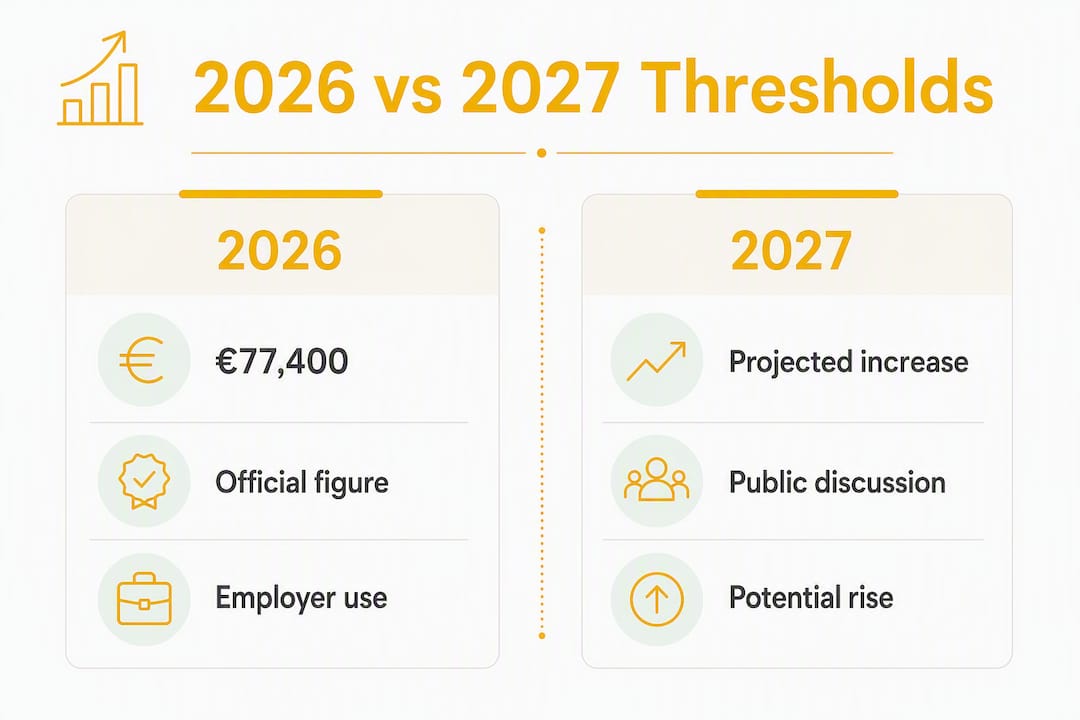
Looking ahead, public discussion in 2026 flagged a potentially substantial 2027 increase, with some commentary suggesting the JAEG could push toward €85,000 in certain scenarios. Nothing is confirmed until the regulation is published, but the direction is clear: the threshold is rising. If you're currently earning just above €77,400, a higher 2027 JAEG could pull you back below the line and end your PKV eligibility for that year. Checking the updated figure each autumn is not optional; it's the kind of detail that changes your insurance status without any warning.
Why does the threshold exist at all? Insurer guidance explains the social-policy rationale: the JAEG is designed to keep lower-income earners in the solidarity-based GKV system, where premiums are income-linked rather than risk-based. Private insurance prices are determined by health risk and age, which can become unaffordable in later life. The threshold is the mechanism that limits who can make that trade-off.
Who can actually opt for private insurance?
The rule applies to employees whose regular gross annual pay exceeds the JAEG. "Regular" is the operative word here. One-off payments don't automatically count, and the classification of your income components matters.
Groups who become eligible to choose PKV when their salary crosses the threshold:
- Standard employees with a regular employment contract whose projected annual gross salary exceeds €77,400 in 2026.
- Employees with multiple jobs where the combined regular income from all positions exceeds €77,400 in 2026.
- New hires whose agreed salary is expected to be above €77,400 from day one in 2026.
Groups who are treated differently or remain in GKV regardless:
- Students in standard student health insurance are subject to separate rules and are generally not eligible for PKV via the JAEG route.
- Civil servants (Beamte) are not covered by GKV compulsory membership rules at all; they access PKV through a different framework (Beihilfe).
- Mini-jobbers earning below the marginal employment threshold are not subject to compulsory GKV membership in the same way and are excluded from this calculation.
- Employees below the threshold remain in compulsory GKV membership regardless of personal preference.
There is also a special lower threshold for employees who were already privately insured on December 31, 2002. Under this Bestandsschutz rule, the special threshold is €69,750 in 2026.
One point worth emphasizing: being "versicherungsfrei" means you are exempt from compulsory GKV membership, not exempt from holding health insurance. You must still be covered, either through voluntary GKV or through a private plan.
What counts toward your annual working remuneration?
The JAEG calculation is based on your regular annual working remuneration, and not every euro that hits your bank account qualifies.
What generally counts:
- Base salary and regular contractual pay increases.
- Regular bonuses that are contractually guaranteed and paid consistently (e.g., a fixed 13th-month payment).
- Taxable allowances that form a regular part of your compensation package.
What generally does not count:
- One-off or discretionary bonuses with no contractual guarantee.
- Overtime pay that is not a fixed, predictable part of your compensation.
- Expense reimbursements and non-taxable benefits.
For part-year employment, the rule uses a projected annual figure. If you start a job in July with a monthly salary of €6,800, the employer projects your annual earnings as though you had worked the full year (€6,800 × 12 = €81,600), which would place you above the 2026 threshold immediately. New hires are assessed on this projected basis, not on what they actually earn in the partial year.
Multiple jobs are combined. If you hold two part-time roles and the combined regular income exceeds €77,400 in 2026, you cross the threshold even if neither job alone would do so.
Pro Tip: Before making any insurance decision, ask your HR department for a written confirmation of how your salary components are classified. Payroll teams determine whether a bonus is "regular" or "one-off," and that classification directly affects your JAEG status. Getting it in writing protects you if the classification is later disputed.
Payroll classification and salary projections are the practical gatekeepers here. Your HR team's determination, not your own estimate, is what your employer reports.
Key dates and deadlines you need to know
Timing is where many employees get caught out. The rules differ depending on whether you're already employed or starting a new job.
For ongoing employment: If your salary crosses the JAEG during the year and is expected to remain above the threshold the following year, your compulsory GKV membership ends at the close of that calendar year, not the moment your salary increases. You then have the choice to join PKV or remain in GKV as a voluntary member. If you do nothing, GKV membership continues automatically as a voluntary membership. A declared exit within the specified notification window allows immediate PKV entry.
For new hires whose agreed salary already exceeds the JAEG, the exemption from compulsory GKV membership is immediate from the first day of employment. You don't wait until year-end.
The two-week window matters. Once you formally declare your intention to leave GKV, you have a short window to arrange PKV coverage and have it take effect without a gap. Missing this window can leave you in a coverage limbo that's difficult to resolve quickly. Notify both your employer and your GKV provider in writing, and confirm the exact deadlines with your insurer.
The September 30 reference that appears in many coverage guides relates to planning for the following year. If you want to switch to PKV at the start of the next calendar year, getting your PKV application, medical underwriting, and formal GKV exit notification completed before the end of September gives you enough runway. Applications submitted later in the year can still work, but the timeline gets tight.
What switching to PKV actually means for you
Moving from GKV to PKV is a significant financial and personal decision, not just an administrative one. The benefits are real for the right profile; so are the risks.
Typical advantages for higher earners:
- Faster specialist access and shorter waiting times in many cases.
- More flexible reimbursement models and broader coverage options, including what private health insurance covers in terms of dental, vision, and specialist care.
- Premiums that are not income-linked, which can be favorable for very high earners who would otherwise pay maximum GKV contributions.
- Individual plan customization, including choice of deductible levels.
Key risks to weigh carefully:
- PKV premiums are risk-based and age-based. They rise as you get older, sometimes sharply.
- Medical underwriting at entry means pre-existing conditions can lead to exclusions or premium surcharges.
- If you have a non-working spouse or children, they are not automatically covered under PKV the way they are under GKV's family insurance. Each family member needs their own policy, which adds significant cost.
- Returning to GKV after switching to PKV is genuinely difficult. After age 55, it becomes extremely hard to return to statutory insurance for most employees.
The age-55 barrier deserves direct attention. Once you're over 55, the legal routes back into GKV are narrow: you'd generally need to become unemployed and meet specific conditions, or your income would need to fall below the threshold while you're still young enough for GKV to accept you. Many people who switch to PKV in their 30s or 40s find themselves locked in by their 50s, paying premiums that have grown substantially while their health situation has changed.
Families with a non-working spouse or planned career breaks often find GKV more cost-effective long-term, even for high earners. The free family coverage in GKV is a benefit that PKV simply doesn't replicate.
Pro Tip: Model your costs over a 20–30 year horizon, not just the next few years. A broker can run a side-by-side long-term projection that accounts for age-based premium increases, family coverage needs, and likely career trajectory. That projection often changes the decision entirely.
Exceptions and special cases that change the picture
The headline rule covers most employees, but several groups operate under different conditions.
-
Bestandsschutz (pre-2003 private members): Employees who were privately insured on December 31, 2002 qualify for a lower threshold. In 2026, that special threshold is €69,750.
-
The over-55 rule: Employees who are over 55 and have been in GKV for most of the preceding ten years generally cannot switch to PKV even if their salary exceeds the JAEG. This is one of the most consequential and least-understood restrictions. It's designed to prevent older, higher-risk individuals from moving into private insurance when GKV has already covered their health costs for decades.
-
Students: Standard student health insurance in Germany operates under a separate framework. Students are generally not eligible to use the JAEG route to access PKV. Those interested in private health insurance as students should check the specific student rules, which differ significantly.
-
Civil servants: Beamte access PKV through the Beihilfe system, which provides a government subsidy toward private insurance costs. The JAEG does not apply to them in the same way.
-
Mini-jobbers and marginal employment: Employees in mini-jobs (below the marginal employment threshold) are not subject to standard compulsory GKV membership rules and are excluded from the JAEG calculation.
Your checklist when your salary crosses the threshold
If your income is approaching the JAEG in 2026, or you're starting a new role above that level, here's what to do:
-
Step 1: Confirm your payroll classification. Ask HR for a written breakdown of which salary components count as regular annual working remuneration. Don't rely on your own estimate.
-
Step 2: Project next year's income. If you're in ongoing employment, the threshold test applies to both the current and following year. Confirm with HR whether your salary is expected to remain above the JAEG in 2027, especially given the anticipated increase.
-
Step 3: Model both options. Compare your current GKV contribution (including the Zusatzbeitrag) against realistic PKV quotes. Factor in family coverage, deductibles, and long-term premium trajectory. A GKV vs PKV comparison can help frame the trade-offs.
-
Step 4: Notify employer and GKV if switching. Submit written notice to both your employer and your GKV provider within the required window. Confirm the exact deadline with your insurer, and keep copies of everything.
-
Step 5: Complete PKV medical underwriting. Obtain quotes from multiple private insurers, disclose your health history accurately, and confirm coverage details including deductibles and family implications before signing anything.
Pro Tip: A broker who handles both GKV and PKV comparisons can run the long-term cost model, manage the notification timeline, and flag underwriting issues before they become problems. The consultation is free, and it typically saves clients from decisions they'd regret at 55.
Key Takeaways
The Versicherungspflichtgrenze (JAEG) is the single most important income threshold in the German health insurance system for employees considering private coverage.
| Point | Details |
|---|---|
| 2026 threshold | The JAEG stands at €77,400 per year; only regular gross salary components count toward this figure. |
| Annual adjustment | The threshold changes every year via the Sozialversicherungs-Rechengrößenverordnung; a substantial 2027 increase has been discussed publicly. |
| Timing rules | Ongoing employees become insurance-free at year-end; new hires with salaries above the JAEG are exempt immediately. |
| Age-55 return barrier | Returning to GKV after switching to PKV becomes extremely difficult after age 55, making the decision effectively permanent for many. |
| Myhealthcarebroker | Myhealthcarebroker provides free eligibility checks, long-term cost modeling, and full application support in English for employees navigating this decision. |
The decision most people get wrong
The most common mistake I see is treating the Versicherungspflichtgrenze as a simple on/off switch. Salary crosses €77,400, switch to PKV, done. The reality is more layered, and the consequences of getting it wrong compound over decades.
Expat professionals in particular often underestimate the family coverage gap. A couple where one partner earns above the threshold and the other is not working pays nothing extra for the non-working partner under GKV. Under PKV, that same family pays a full additional premium for the non-working partner. For a family with two children, the cost difference can be substantial enough to make GKV the smarter financial choice even at salaries well above the threshold.
The age trap is the other pattern I see repeatedly. Employees in their late 30s switch to PKV attracted by lower premiums and better access, then find themselves in their mid-50s with rising premiums, changed health circumstances, and no practical route back to GKV. The decision that felt right at 38 can feel very different at 54.
The JAEG gives you a choice. It doesn't tell you which choice is right. That depends on your age, family structure, health history, career trajectory, and long-term financial plan. Getting those variables into a model before deciding is the difference between a good outcome and an expensive lesson.
How Myhealthcarebroker helps you navigate this decision
Crossing the Versicherungspflichtgrenze is the starting point, not the finish line. Myhealthcarebroker offers exactly the kind of independent, English-language support that makes the next steps manageable: a free eligibility check to confirm whether you qualify for PKV, a side-by-side long-term cost model comparing your current GKV contributions against realistic PKV quotes, and full application support from underwriting through to policy activation.
Unlike going directly to a single insurer, Myhealthcarebroker compares options across all major private providers, so you see the full picture rather than one company's best offer. The service is free to you; the broker is paid a regulated commission by the insurer only when a policy is placed. Use the PKV cost calculator to get an immediate estimate, or visit the private health insurance guidance page to book a short consultation and get your questions answered in plain English.
This article is general information, not professional legal or financial advice. Confirm current thresholds and your personal eligibility with your HR department, your GKV provider, or a qualified insurance advisor before making any changes to your coverage.
Useful sources
The figures and rules in this article come from primary German government and regulatory sources. Use these to verify current numbers and follow up on specific questions.
| Source | What it covers |
|---|---|
| Jahresarbeitsentgeltgrenze, Wikipedia (DE) | Definition, annual adjustment methodology, and historical figures for the JAEG |
| Bundesgesundheitsministerium (BMG) | Official government page on statutory health insurance membership, timing rules, and the two-week notification window |
| ERGO: Was ist die Versicherungspflichtgrenze? | Insurer guidance on the social-policy rationale and practical implications of the threshold |
| Myhealthcarebroker: 2027 income threshold analysis | Client-facing analysis of 2027 JAEG proposals and what employees should do now |
| Myhealthcarebroker: GKV vs PKV comparison | Side-by-side breakdown of statutory and private insurance differences |
| Myhealthcarebroker: PKV cost calculator | Interactive tool for modeling PKV vs GKV costs based on your personal situation |