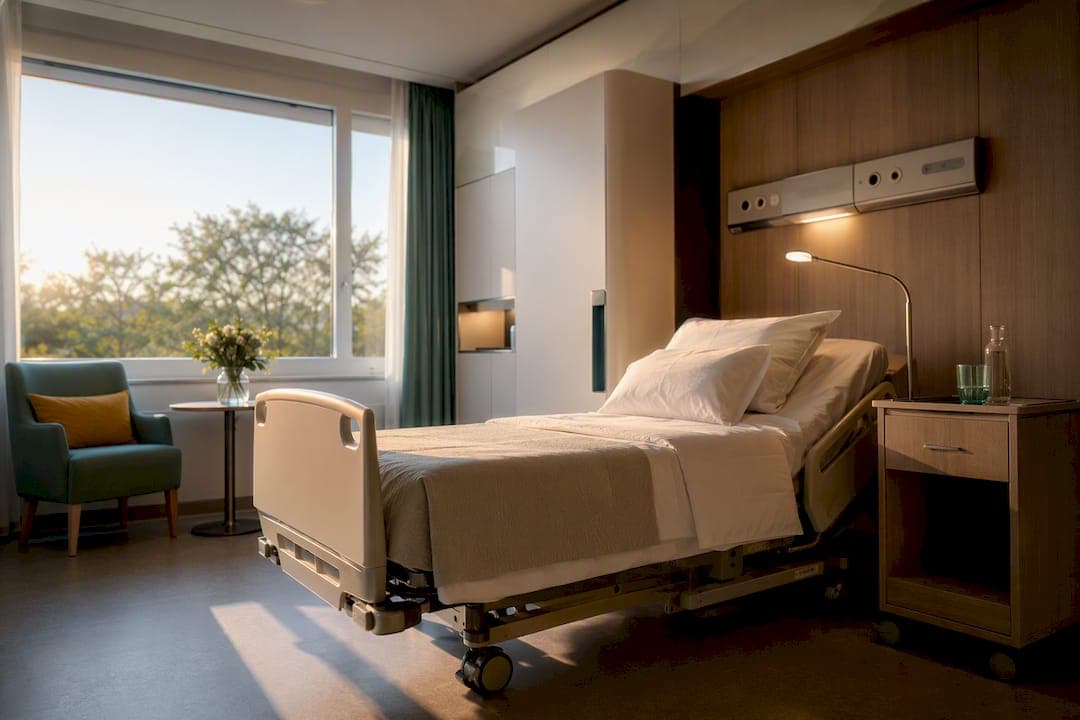
Yes, being a Privatpatient in Germany delivers real, tangible benefits: faster specialist access, free choice of doctor and hospital, and contractual hospital extras called Wahlleistungen. The trade-off is real too. Private premiums run on age and health risk rather than income, and they can climb steeply later in life. Whether you should choose PKV over GKV depends less on the label and more on the specific tariff you buy.
TL;DR:
- Private health insurance premiums are based on age and health risk, often increasing significantly as you get older, regardless of income.
- Wahlleistungen, such as single rooms and direct access to senior physicians, require a separate contract and are subject to hospital approval and upfront payments.
- Faster specialist appointments for private patients depend on regional and specialty factors, with many specialists in certain fields working exclusively with private clients.
- High-end private tariffs may reimburse more for dental and optical treatments, but coverage for psychotherapy is often better under statutory insurance plans.
- Long-term costs for PKV can rise sharply in retirement due to inflation and aging, especially since premiums are fixed at entry and not affected by income.
Table of Contents
- What Are the Practical Benefits of Privatpatient Status?
- How Do Wahlleistungen Actually Work in a Hospital?
- Why Do Private Patients Get Faster Specialist Appointments?
- Where Does PKV Coverage Actually Outperform GKV?
- What Do PKV and GKV Actually Cost in 2026?
- What Long-Term Risks Should Factor Into Your Decision?
- How Should You Compare PKV Tariffs Before Deciding?
- How Does Independent Broker Advice Simplify This Decision?
- What the Data Actually Supports About Privatpatient Status
- Get a Tailored PKV Comparison Before You Decide
- Sources
What Are the Practical Benefits of Privatpatient Status?
The Privatpatient Vorteile that actually show up in daily life fall into five categories, and most of them come down to how quickly you're seen and how much comfort you get once you are.
Private billing gives doctors an incentive that the statutory system doesn't: paid promptly, without the budget caps that limit how many GKV patients a practice can see per quarter. That's the mechanical reason behind most of the benefits listed below.
- Shorter waits for specialists and diagnostics. Elective MRI scans, dermatology consults, and orthopedic follow-ups often come through in days rather than weeks.
- Free choice of doctor and clinic, including access to private specialists who don't accept statutory patients at all.
- Hospital Wahlleistungen, meaning single or double rooms and treatment directly from the senior physician (Chefarztbehandlung) rather than whoever is on rotation.
- Broader dental and optical coverage, depending on tariff, sometimes covering high-end prosthetics or premium lenses that GKV caps sharply.
- Faster access to some newer therapies and diagnostic technology that hasn't yet cleared the statutory system's approval and reimbursement process.
None of this means private medicine is medically superior. It means you get more comfort, more choice, and often more speed for non-urgent care. That distinction shapes almost everything else in this guide.
How Do Wahlleistungen Actually Work in a Hospital?
Wahlleistungen are not automatic. When you're admitted, the hospital presents a Wahlleistungsvereinbarung, a separate contract you sign specifically to unlock the extras your tariff covers. Skip that step, and you get standard care, even as a private patient, according to Pkv.
Chefarztbehandlung means the department's senior physician personally oversees your case rather than delegating it entirely to residents. In practice, this often means more direct conversations with the most experienced person on staff, plus separate billing under the GOÄ private fee schedule.
- Single or double rooms, sometimes with better food service and visiting hours.
- Personal choice of surgeon or lead physician for planned procedures.
- Access to a wider range of elective diagnostic add ons during your stay.
Emergency care doesn't follow any of this. Triage in a German emergency room runs on medical urgency, not insurance status, according to Versicherungswerk. A heart attack gets the same immediate response whether you're privately or statutorily insured.
Pro Tip: If comfort in a hospital stay matters to you but you'd rather stay in GKV, ask about Krankenhauszusatzversicherung, a supplemental policy that buys Wahlleistungen without switching your entire insurance system.
Some hospitals also require upfront payment or separate invoicing for Wahlleistungen depending on your specific tariff, a detail worth confirming before admission, according to AXA's hospital guidance.
Why Do Private Patients Get Faster Specialist Appointments?
The speed difference is structural, not preferential. Contract doctors treating GKV patients operate under quarterly budget caps set by their Kassenärztliche Vereinigung. Once a practice hits its cap for statutory reimbursement in a given period, seeing more GKV patients becomes financially unattractive. Private billing has no such ceiling.
That's why some specialists, particularly in dermatology, orthopedics, and certain surgical fields, work exclusively with private patients. They simply don't accept GKV referrals at all.
- Private patients often report booking a specialist appointment more quickly than under GKV for the same non-urgent issue.
- Speed varies heavily by region and specialty; rural areas often show smaller gaps than cities like Munich or Frankfurt.
- Referral behavior differs too. GKV patients typically need a Hausarzt referral for many specialists, while private patients can often book directly.
None of this applies to acute or urgent cases, where German medicine treats everyone on the same timeline.
Where Does PKV Coverage Actually Outperform GKV?
The honest answer is: it depends entirely on which tariff you're comparing, not which system you're in. A well-structured PKV plan can beat GKV comfortably in some categories and lose to it in others.
Dental is the clearest example. High-end PKV tariffs can reimburse a much larger share of prosthetics, implants, and ceramic crowns, categories where GKV's fixed subsidies leave a meaningful gap for the patient to cover. Optical coverage follows a similar pattern; premium tariffs sometimes fund progressive lenses or frames that GKV treats as a minor, capped allowance.
Psychotherapy tells the opposite story. GKV's structured system guarantees a defined number of session types with predictable approval processes. Entry-level PKV tariffs sometimes cap session counts or require pre-approval that can feel more restrictive than the statutory system, according to Nextsure's analysis. If mental health coverage matters to you, read the tariff details on psychotherapy benefits before assuming private automatically means better.
- Dental prosthetics: premium PKV tariffs often reimburse a much larger portion than GKV's fixed subsidy.
- Optical aids: coverage varies widely by tariff, from minimal to generous.
- Psychotherapy: GKV's structure can outperform low-tier PKV plans.
- Medical devices and rehab: mid-to-high PKV tariffs tend to offer more flexibility, but not universally.
The tariff itself determines the real benefit, not the Privatpatient label alone.
What Do PKV and GKV Actually Cost in 2026?
The two systems price risk in completely different ways, and that difference is the single biggest factor in whether PKV pays off for you.
GKV contributions run on income. In 2026, the base rate is 14.6%, plus an average Zusatzbeitrag of about 2.9%, for a combined rate near 17.5% of gross salary, split between you and your employer. That contribution is capped once you earn above the Beitragsbemessungsgrenze, set at €5,812.50 per month, according to Handelsblatt. Earn more than that, and your GKV contribution stops rising with income.
PKV works the opposite way. Your premium is fixed at the point of entry based on your age, your health at underwriting, and the tariff you select. It has nothing to do with how much you earn. A healthy 28-year-old and a 28-year-old with a chronic condition applying for the same tariff will pay very different premiums, and once you're in, your income going up doesn't raise your bill.
In numbers: GKV contributions cap out around €1,017 per month combined at the Beitragsbemessungsgrenze of €5,812.50. PKV premiums, by contrast, are set individually and can sit well below or well above that figure depending entirely on age and health at entry.
Your employer's contribution matters here too. Under German law, employers pay up to half of the GKV maximum contribution toward a private employee's PKV premium, capped at that same statutory ceiling. If your PKV tariff costs more than double the GKV cap, you absorb the difference entirely yourself.
- Young, healthy, high earners often see genuine savings, since their risk-based premium starts low and their income would otherwise be capped anyway under GKV.
- Certain civil servants (Beamte) benefit structurally because the state covers a large share of costs through Beihilfe, making PKV the more economical complement.
- Families with children frequently pay more overall in PKV, since each child needs a separate premium; GKV covers dependents at no extra cost, a point Finanztip emphasizes for household planning.
- Older entrants face higher starting premiums simply because underwriting reflects the actuarial reality of age.
What Long-Term Risks Should Factor Into Your Decision?
PKV insurers build Altersrückstellungen, reserves collected early in your policy specifically to soften the premium increases that come with age. These reserves help, but they don't eliminate the underlying pressure. Medical cost inflation and an aging risk pool still push premiums upward over time, according to Klinikkosten's guide.
That upward drift becomes a real affordability question in retirement, when income often drops just as your premium history reaches its highest point. This is the scenario Finanztip's analysis flags most consistently: PKV can look attractive at 30 and feel burdensome at 68.
- Returning to GKV becomes difficult, and after age 55 it's generally restricted to specific circumstances, such as falling below the income threshold or certain employment changes.
- PKV offers no free family coverage. Each child and non-earning spouse needs a separate premium, unlike GKV's dependent coverage.
- Premium increases aren't optional extras. They're a structural feature of how risk-based insurance prices an aging population.
Pro Tip: Before enrolling in PKV, ask the insurer for a projected premium at ages 50, 60, and 70, not just your entry price. Most applicants only ever see the starting number.
If children are part of your near-term plans, compare the full statutory versus private breakdown before committing, since family costs shift the math substantially.
How Should You Compare PKV Tariffs Before Deciding?
Comparing tariffs properly takes more than checking a monthly price. Here's the order that actually protects you from a bad decision:
- Confirm eligibility first. Income thresholds, employment status, and Beamte status all affect whether PKV is even available to you.
- Run multiple quote scenarios, not just one insurer's number, since risk-based pricing varies significantly between providers for the same health profile.
- Check inpatient Wahlleistungen line by line, including room type and Chefarztbehandlung, rather than assuming "private" automatically includes both.
- Review dental coverage percentages and any waiting periods before major treatments are reimbursed.
- Ask about exclusions tied to pre-existing conditions, since underwriting can limit or surcharge coverage for specific issues.
- Request a projected premium trajectory, not just the entry price, covering at least two future decades.
When you're on the phone with an insurer or broker, ask directly: how are Altersrückstellungen calculated for this tariff, what's the historical contribution trend for this plan, how exactly does the employer subsidy apply to my premium, and what would a spouse or child cost under this same tariff?
Pro Tip: Treat vague answers about future premium trends as a red flag. A tariff that can't show you a realistic long-term trajectory is asking you to buy blind.
How Does Independent Broker Advice Simplify This Decision?
Comparing PKV tariffs properly means modeling age-based premium trajectories, employer subsidy limits, and family costs across multiple insurers simultaneously, work that's genuinely hard to do accurately on your own. That's the gap independent brokers fill.
An independent broker runs eligibility checks, compares tariffs across major private and public insurers, and walks through exactly how employer subsidies and family costs apply to your specific numbers. Clients get a customized comparison in plain English, worked examples against their actual salary and family situation, and support through the application itself.
The model is transparent: the broker earns a fixed, regulated commission from the insurer when you sign up, so the comparison itself costs you nothing.
What the Data Actually Supports About Privatpatient Status
The strongest case for PKV isn't comfort or prestige. It's the mechanical reality that private billing removes the budget caps constraining GKV specialists, which is why appointment speed is the most consistent, verifiable advantage across the system. Everything else, room type, Chefarztbehandlung, dental extras, depends entirely on the tariff you buy.
Conventional advice treats "going private" as a single decision. It isn't. A 26 year old software engineer and a 45 year old parent of two are answering completely different financial questions, even if they're both asking about the same insurance category. The engineer's math often works because premiums start low and stay flexible. The parent's math often doesn't, because family coverage and long-term premium drift work against them.
If you take one thing from this guide, prioritize the premium trajectory over the sign-up price. Insurers show you an attractive number at 30. Almost nobody shows you the number at 65 unless you ask for it directly, and that's the number that determines whether this decision ages well.
— Marco
Get a Tailored PKV Comparison Before You Decide
If you're an expat, a high earner, a student, or a Beamte weighing PKV against GKV, running the numbers on your own situation beats guessing based on generic advice.
An independent broker compares tariffs across all major private and public insurers in Germany, in English, and shows you the actual trade offs for your income, age, and family situation, not just a marketing brochure's version of them. The process starts with a free eligibility check, moves through a side by side comparison of realistic tariff scenarios, and continues into application support if you decide to move forward. Since the service runs on a regulated commission paid by the insurer, there's no cost to you at any stage.
Run the private health insurance calculator for an instant estimate, or go straight to a tailored comparison of Germany's insurers to see how your specific numbers actually play out over the next several decades.
Sources
- Handelsblatt — PKV oder GKV comparison
- Finanztip — Krankenversicherung guide
- Pkv
- Versicherungswerk — Privatpatient im Krankenhaus: Vorteile
- Klinikkosten — PKV vs GKV guide