Yes, you can apply to be exempted from compulsory statutory health insurance, but only in specific situations defined by § 8 SGB V, and only if you act fast. You have a limited period from the date your insurance obligation begins to file the application, and you must prove you already have equivalent alternative coverage lined up. Once approved, the decision is generally permanent and cannot be revoked later on for reasons like premium changes.
TL;DR:
- Exemption applications must be filed within a limited period after insurance obligation begins and require proof of equivalent private coverage.
- Common qualifying events include income crossing the threshold, university enrollment, unemployment benefits, internships, and certain employment situations.
- Supporting documents include completed forms, private insurer confirmation, proof of the triggering event, and benefit letters, all in German or properly translated.
- Exemptions are generally permanent and cannot be revoked easily, and leaving GKV later requires specific qualifying events.
- Filing late, incomplete documentation, or inadequate proof of coverage are primary reasons for application rejection, making early, thorough preparation essential.
Table of Contents
- What Is Befreiung Von Der GKV and Who Can Apply?
- What Documents Do You Need for Befreiungsantrag GKV?
- How Do You File and How Long Does It Take?
- What Are the Long-Term Effects of Exemption?
- How Do These Rules Play Out in Real Cases?
- How My Healthcare Broker Reviews Exemption Applications
- Get Your Free GKV Exemption Eligibility Check
- Where to Find the Official Rules and Forms
- Sources
What Is Befreiung Von Der GKV and Who Can Apply?
Befreiung von der GKV means release from the legal duty to be a member of Germany's statutory health insurance system, sometimes called an "exemption from health insurance" or "GKV exclusion." It isn't a general opt-out available to anyone who dislikes their Krankenkasse. The right to apply exists only when a specific triggering event puts you into compulsory insurance in the first place, and § 8 SGB V lists exactly which events qualify.
The most common qualifying categories include:
- Crossing the annual income threshold (JAEG): if your gross salary rises above the compulsory insurance limit and you were previously privately insured, you can apply to stay out of GKV.
- Starting studies as a registered student: enrollment at a German university triggers statutory insurance obligation, and you can apply for exemption if you already hold private coverage.
- Certain unemployment or benefit situations: if you start receiving unemployment benefits and were not covered by GKV for the five years before that, you may qualify.
- Practicums and mandatory internships: some structured training placements create insurance obligation with a corresponding exemption right.
- Work in facilities for people with disabilities: employment in these settings can trigger GKV duty, with the same exemption option attached.
- Reduced working hours after long-term private coverage: a shift to part-time work, including around parental leave, can create a new compulsory insurance event.
The tricky part is distinguishing a temporary change from a permanent one. A short stretch of reduced hours during parental leave often triggers only a temporary insurance obligation, while a permanent switch to part-time work is treated differently by your Krankenkasse. If you're unsure which bucket you fall into, that ambiguity is exactly where applications get rejected. Readers weighing statutory versus private coverage in general should treat this section as the first filter, not the last word.
What Documents Do You Need for Befreiungsantrag GKV?
Your Krankenkasse won't take your word for it. Every exemption application needs paper behind it, and missing even one piece is the fastest way to get a rejection letter instead of an approval.
- A completed and signed application form, using either your Krankenkasse's own template or a standard version like the BKK sample application, which shows exactly which fields and declarations insurers expect.
- Proof of equivalent alternative coverage, typically a confirmation letter from your private insurer, or documentation of Beihilfe entitlement if you're a civil servant.
- Evidence of the triggering event, such as an employer statement or recent pay slips showing your salary crossed the JAEG threshold, or a university enrollment confirmation.
- Benefit decision letters, if your application is based on an unemployment or benefit scenario, showing the start date and your insurance history.
"Equivalent coverage" means your private policy has to offer benefits broadly comparable to GKV, not a bare-bones travel plan. Krankenkassen check this specifically, and a thin policy can sink an otherwise solid application. If any document is in a language other than German, get it translated properly. Resources like PolishMyGerman's free materials can help non-native speakers get official paperwork into shape before submission.
Pro Tip: Request a written confirmation letter from your private insurer well before your deadline. Some insurers take a week or more to issue it, and a late confirmation letter can cost you the whole three-month window.
How Do You File and How Long Does It Take?
You must start the filing deadline from the day your insurance obligation begins, not the day you decide to look into it. Missing the filing deadline means you lose the right to exemption tied to that specific event permanently, though a future qualifying event could open a new door.
You can file the application through several channels:
- Postal submission directly to your Krankenkasse.
- In-person at a local branch office.
- Through your Krankenkasse's online portal, where available.
Krankenkassen like AOK and DAK are required to process the application and notify you of the outcome, and the application itself is free. What happens next depends on your usage history: if you haven't used any statutory health services since your obligation began, the exemption can apply retroactively to your start date. If you have used services, even one doctor's visit, the exemption typically only takes effect from the first day of the month after you file. That single detail trips up a lot of applicants who assume retroactivity is automatic.
If you're preparing to move to private cover once exempted, the documentation habits described in applying for private health insurance in Germany line up closely with what your Krankenkasse will ask for anyway.
What Are the Long-Term Effects of Exemption?
An approved exemption is, for practical purposes, a one-way door. § 8 SGB V does not build in a general right to revoke the decision, and both the statute and government guidance for students treat it as a long-term commitment rather than a trial run.
The permanence problem: once you're exempted, your spouse and children cannot be covered under GKV through you either. If your household relied on family co-insurance, exemption removes that path entirely, and everyone needs their own private arrangement.
Returning to GKV later is possible, but only under specific conditions, usually another qualifying event like your income dropping below a certain level. That process is its own maze, covered in detail in the guide on returning to GKV when income falls. If your circumstances feel unstable, that's the moment to get advice before you file, not after.
How Do These Rules Play Out in Real Cases?
The categories in § 8 SGB V read like dry legal language until you see them applied to an actual person's paperwork.
- The student: enrolls at a German university, already has private coverage from home, and files enrollment proof plus the private insurer's confirmation within three months of registering. Family members are not automatically protected, so a spouse needs their own policy too.
- The JAEG case: an employee's salary rises above the compulsory insurance threshold, and because they were privately insured before joining GKV, they can apply to stay private, provided the employer statement documenting the raise is included.
- The benefit recipient: starts receiving unemployment benefits, but only qualifies if they weren't in GKV for the five years prior, a rule that often surprises people who assume any benefit period automatically triggers compulsory insurance.
- The parental leave case: temporarily reduces working hours, which may create a short-term insurance obligation. The application needs to specify that the reduction is time-limited, not permanent, or the Krankenkasse may treat it differently.
How My Healthcare Broker Reviews Exemption Applications
Marco has spent years inside Germany's insurance bureaucracy, and one pattern shows up constantly: people don't lose their exemption because they were ineligible, they lose it because the paperwork was late or thin.
At a consultancy like Myhealthcarebroker, the review process starts with an eligibility check against the § 8 SGB V categories, then moves to verifying that a private policy is genuinely equivalent to GKV coverage, not just cheaper. The three most common mistakes seen repeatedly are filing after the three-month deadline, submitting an insurer confirmation letter that doesn't clearly state coverage scope, and forgetting to check what exemption means for a spouse or children on family coverage. Catching those three issues before submission is often the difference between an approval and a rejected application that can't be resubmitted for the same event.
— Marco
Get Your Free GKV Exemption Eligibility Check
Filing an exemption application without knowing exactly where you stand is a gamble with a three-month expiration date. Myhealthcarebroker offers a free eligibility check that walks through your specific triggering event, reviews whether your current or prospective private policy counts as equivalent coverage, and flags any documentation gaps before you submit anything to your Krankenkasse.
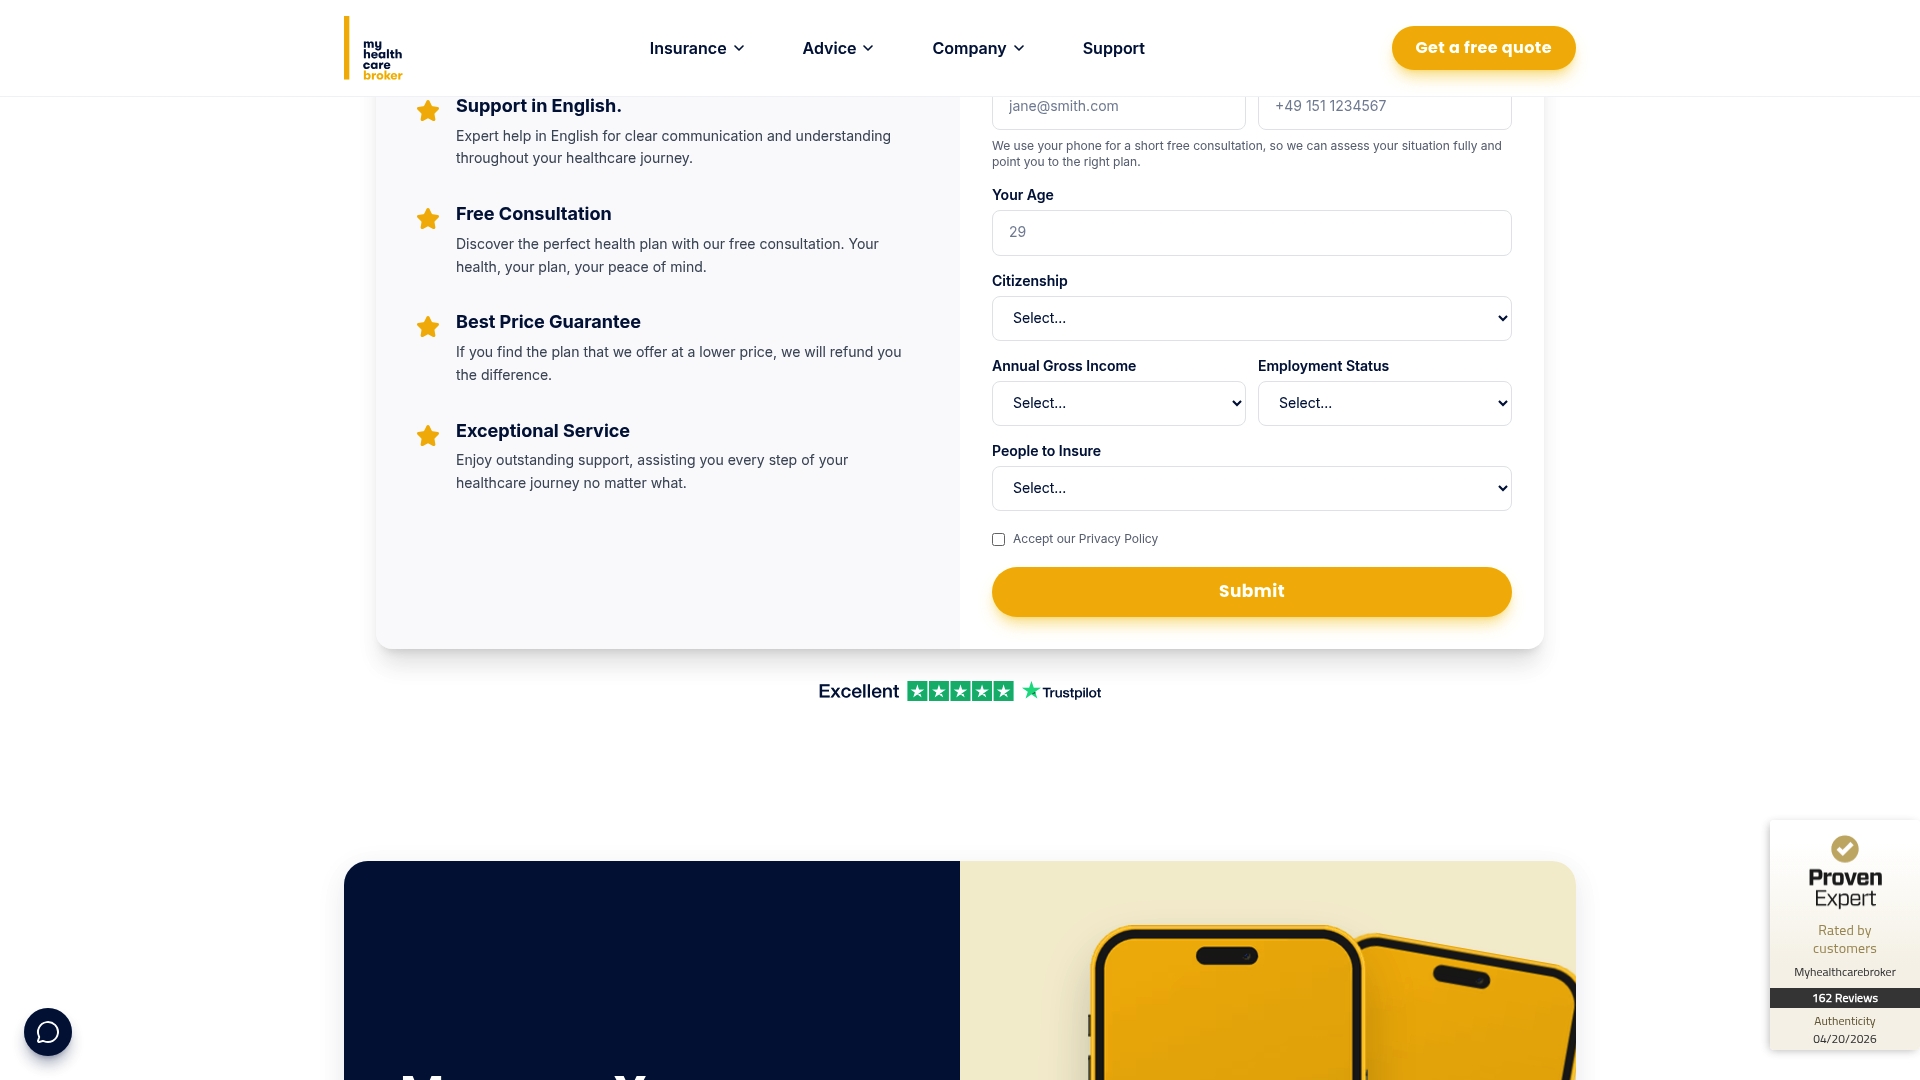
This is especially useful if you're an expat unsure which § 8 SGB V category applies to you, if your insurance history mixes GKV and private periods in a way that's hard to untangle alone, or if you're a student weighing whether private coverage actually makes sense for your situation. Because Myhealthcarebroker compares options across major German insurers and works independently of any single provider, the advice you get reflects your circumstances, not a sales quota. Start with a free eligibility check for private health insurance in Germany and find out exactly where you stand before your deadline closes.
Where to Find the Official Rules and Forms
- § 8 SGB V legal text: the statute itself, covering the deadline, retroactivity, and irrevocability.
- Verwaltungsportal Bund guidance: official government explanation of the exemption process.
- AOK application page and the BKK sample PDF: real forms showing the exact fields to complete.
Sources
- Befreiung von der Versicherungspflicht in der gesetzlichen Krankenversicherung (Verwaltungsportal Bund)
- § 8 SGB V Befreiung von der Versicherungspflicht (SGB text)
- Antrag auf Befreiung von der Versicherungspflicht (AOK)
- Antrag auf Befreiung von der Krankenversicherungspflicht (BKK DA sample PDF)